Car insurance costs an average of $148 a month for full coverage in the U.S. — about $1,770 a year — but that national number won't tell you much about your own bill. Depending on your state, driving record, vehicle, and credit, a fair monthly payment could land anywhere from $40 to $350 or more. Here's what actually moves that number, and how to tell if what you're paying is reasonable.
There's no single answer to how much car insurance should cost, because insurers price every policy differently. Your monthly premium is really your annual cost split into 12 payments, and that annual figure depends on:
An auto insurance policy with only liability coverage sits at the low end of the ranges below. Add comprehensive and collision, plus extras like rental reimbursement or roadside assistance, and the same policy can run two to three times as much per month. That's why two drivers in the same city can get a completely different car insurance quote for what looks like similar coverage — the insurance coverage itself isn't the same, even if the sticker price looks comparable.

Where you live significantly impacts your insurance premiums. Here's a snapshot of average annual full coverage premiums in different states:
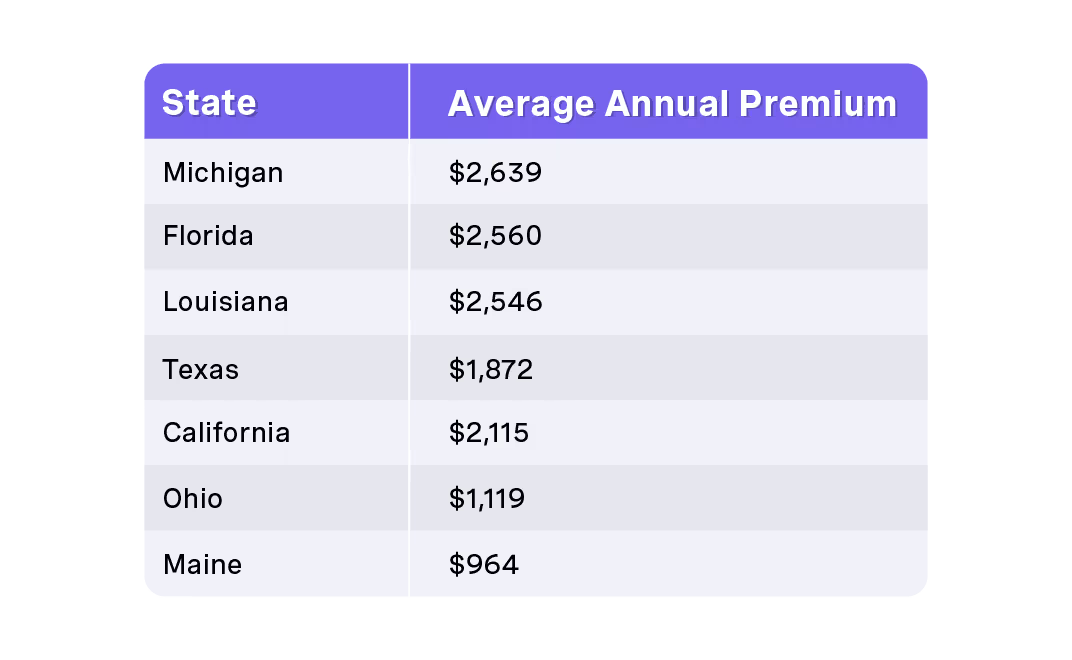
These differences exist because of varying:
If you're a Texas resident, check out our guide to Texas car insurance for state-specific insights.
The more coverage you have, the more you'll pay. Basic liability coverage costs significantly less than full coverage with comprehensive and collision.
Additional coverages like rental reimbursement or roadside assistance will increase your premium further.
Your driving history is one of the most influential factors in determining your rate. Maintaining a clean driving record is one of the most effective ways to keep your insurance premiums down.

Maintaining a clean driving record is one of the most effective ways to keep your insurance costs down.
The make, model, year, and even color of your car affect your premium:
Before buying a new car, consider checking its insurance costs using our car insurance calculator.
Age significantly impacts insurance rates, particularly for young drivers:
Young drivers pay more because statistics show they're more likely to be involved in accidents. Good student discounts and safe driver programs can help offset these higher rates.
In most states, insurers use credit-based insurance scores to help determine premiums. Drivers with poor credit may pay 40–50% more than those with excellent credit.
This practice has been controversial, and some states (like California, Hawaii, and Massachusetts) have banned it. If you're working to improve your credit, OCHO's on-time payment reporting can help build your credit score over time.
Even within the same state, premiums can vary significantly:
For example, car insurance in Houston might cost 15–20% more than in rural areas of Texas.
While the "right" price varies widely, here are some benchmarks based on coverage level and driver profile:
Minimum Liability Coverage
Full Coverage (Comprehensive + Collision, $500 deductible)
These are general ranges. Your actual rates could be higher or lower depending on your specific circumstances and the average annual cost insurers assign to your risk profile.
Price isn't the only variable worth getting right. Your coverage limits determine how much protection you have if you're in an accident, and setting them too low is its own way of overpaying, just in the form of risk instead of premium.
State minimums only cover the other driver's costs, and often not by much. If you're carrying a car loan or lease, your lender will usually require comprehensive and collision coverage on top of that, since it protects the vehicle itself, not just other people. Even if your car is paid off, comprehensive and collision are worth keeping until the car's value drops low enough that a claim payout wouldn't be worth much anyway.
A simple way to sanity-check this: run your numbers through a car insurance calculator using your actual coverage limits, not just the state minimum, so the estimate reflects what you'd really need rather than the cheapest legal option. It's also worth pulling a few line items from past car insurance claims data for your area (your agent or insurer can usually share average claim payouts by coverage type) so you're setting limits based on real numbers, not guesswork.
Once you know what coverage you actually need, that's the point to compare car insurance quotes, not before. Shopping on price alone, before you've settled on coverage limits, is how a lot of drivers end up underinsured in the first place.
How do you know if you're overpaying? Watch for these red flags:
If any of these apply to you, it's time to shop around using our car insurance comparison tool.
Most insurers offer various discounts that can significantly reduce your premium:
Ask about all available discounts when getting a car insurance quote — they can add up to meaningful savings.
Finding the right balance between coverage and cost is key:
OCHO is a licensed insurance broker and premium finance lender, and we work to make paying for car insurance more manageable, not just the coverage itself:
While it's important not to overpay, being underinsured can cost you far more in the long run. Consider this example:
Scenario: You choose minimum liability coverage ($30,000) to save money, then cause an accident resulting in $50,000 of damage to another vehicle.
Result: Insurance covers $30,000, but you're personally responsible for the remaining $20,000, plus your own vehicle repairs.
The extra $10–$20 a month for higher coverage limits could save you from a financial setback in this scenario. Similarly, skipping comprehensive coverage might save $20–$40 a month but leave you with no coverage if your car is damaged by hail or another non-collision event.
So, how much is car insurance per month? For most drivers with decent credit and a clean record, a fair full-coverage payment lands somewhere between $100 and $180 a month, with minimum coverage landing well under $100. Your own number depends on where you live, what you drive, and how you've driven so far, but you shouldn't be paying more than that without a clear reason why.
At OCHO, we believe everyone deserves a path to affordable coverage with payment terms that match their financial reality. Get a free quote today and see what a monthly payment could look like for you.
Compare & get covered fast
Find and compare auto insurance in minutes, and get your free credit score.
Choose when you pay
Select payment dates that line up with your payday.
Manage everything in one place
Track your policy, manage payments, and request a payment extension right from your dashboard.