South Carolina drivers pay more for car insurance than the national average, and the state's requirements go beyond what most states demand. This guide covers what you need to carry, what it costs, and how to keep those costs under control.
Every vehicle registered in the state must carry active insurance in South Carolina. The South Carolina Department of Insurance regulates all policies, and every insurance company selling auto coverage must be licensed within the state.
South Carolina is an at-fault state. If you cause a car accident, your liability coverage is on the hook for the other person's bodily injury and property damage. Unlike no-fault states that rely on PIP to cover each driver's own medical expenses, South Carolina puts the financial burden on whoever caused the crash. The 25/50/25 minimum mirrors what many other states require, but those limits run out fast when a serious collision involves multiple vehicles, hospital stays, or totaled cars.
Before you purchase a policy, review the declarations page so you understand exactly what your insurance coverage includes and what it excludes, and make sure you understand the different types of car insurance coverage available to you.
To drive legally and register a vehicle in South Carolina, you must carry specific minimum coverage. You cannot register a vehicle without proof of insurance; the state electronically verifies your policy status.
South Carolina requires minimum coverage of 25/50/25:
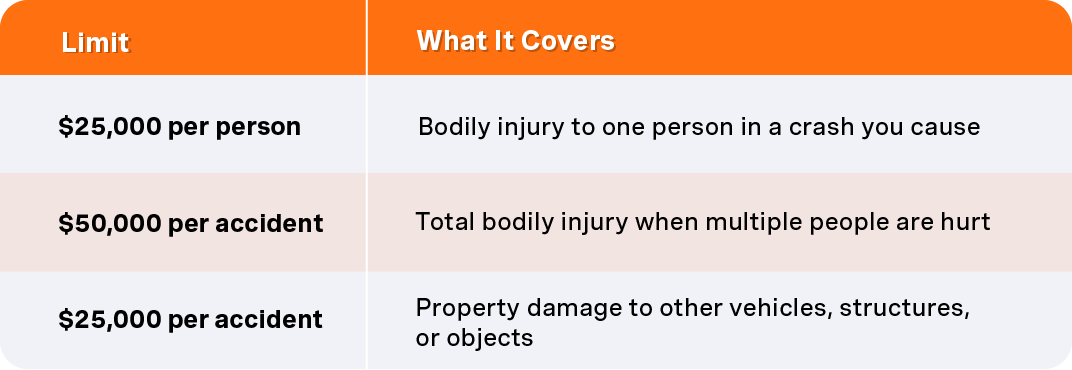
If you rear-end two cars and three people need emergency care totaling $70,000, your $50,000 cap leaves you personally liable for the remaining $20,000. Drivers are encouraged to obtain higher liability limits than the state minimum for financial protection; options like 100/300/100 better shield your assets from lawsuits and highlight why car insurance is so important in real life.
South Carolina requires uninsured motorist coverage for all drivers at matching 25/50/25 limits, with a $200 deductible on property damage claims. This coverage helps pay your medical bills and repair costs when a hit-and-run or uninsured driver causes the crash.
Underinsured motorist coverage is not mandatory in South Carolina. Your insurer must offer it, but you can decline. South Carolina allows drivers to "stack" underinsured motorist (UIM) coverage under specific conditions, which can increase available limits if you have multiple vehicles on one policy. UIM becomes critical when the at-fault driver's insurance policy maxes out well below your actual medical expenses.
Proof of insurance is required at traffic stops, after any accident, during vehicle registration, and for driver's license transactions. Electronic ID cards on your phone are accepted. If your coverage lapses, expect a $200 reinstatement fee plus a fine of $5 per day (up to $200 for a first offense), and higher future auto insurance rates.
Insurance costs vary based on coverage, car, and driving record. Full coverage costs considerably more than a minimum liability-only policy, and your exact price depends on your profile. Comparing quotes from several insurers is the best way to see where you land.
Insurers evaluate multiple factors such as driving record and geographic territory to determine rates. Here's how several factors move the needle:
State law mandates specific types and minimum limits of auto coverage (liability and UM). Everything else is optional coverage, though lenders almost always require physical damage protection on financed or leased vehicles.
Required:
Optional:
Choosing a $1,000 deductible instead of $500 on collision and comprehensive lowers your premium, but make sure you can cover that amount if you file a claim. The actual cash value of your vehicle (its current market value) determines the payout ceiling on a total loss.
South Carolina car insurance runs high, but several factors are within your control.
An existing policy should be reviewed annually. Don't just chase the cheapest quote; confirm your limits still match your financial exposure.
South Carolina uses a modified comparative negligence system for damages recovery. If you're partly at fault for a car accident, your compensation is reduced by your fault percentage. At 20% fault, you recover 80% of damages. If you're 51% or more at fault, you recover nothing.
Penalties for no insurance are steep. A first offense carries a fine of $100 to $200 or 30 days in jail. Your license and registration may be suspended for no insurance. If you own the vehicle, your license and registration stay suspended until you pay a reinstatement fee, which starts at $600 and is adjusted each year by the South Carolina Department of Insurance. If you knowingly drive someone else's uninsured car, expect a 30-day license suspension. Drivers must maintain continuous insurance coverage to avoid penalties in South Carolina; fines for driving without insurance can reach up to $200, and the South Carolina Department of Motor Vehicles will suspend your registration if coverage cannot be verified.
After a crash:
An insurance adjuster inspects damage or reviews repair estimates. You can choose any repair shop; you're not required to use the insurer's preferred network. If your policy includes rental reimbursement, it covers a rental car while repairs are underway. If the other driver was at fault, their liability policy may also cover your rental costs; understanding when insurance pays for a rental car during repairs helps you avoid surprise out-of-pocket expenses.
Yes. You cannot register a vehicle without proof of insurance from a company licensed in South Carolina. Your insurer reports your policy to the SCDMV electronically. If coverage is canceled or lapses, the South Carolina Department of Motor Vehicles can impose fees or suspend your registration until you restore proof of coverage.
Most moving violations and at-fault accidents influence auto insurance rates for about three years. Serious offenses like DUIs can affect pricing for five years or longer. Each insurer's rating program is different, so ask your insurance company how long a specific infraction will impact your premium.
No. South Carolina is an at-fault (tort) state. The driver who causes the car accident is responsible for paying for injuries and property damage through their liability coverage. Injured drivers can file claims directly with the at-fault driver's insurer or pursue a personal injury lawsuit if the at-fault driver's coverage is insufficient.
In most states, insurance follows the car rather than the driver. The vehicle owner's policy is typically primary when a permitted driver borrows the car. Coverage details vary by policy, so contact your insurance company and confirm the owner's existing policy covers permissive use before you drive regularly; a detailed guide on whether insurance covers you when driving someone else's car can help clarify gaps.
New residents have 45 days after establishing domicile to register their motor vehicles and obtain SC license plates. You must purchase car insurance in South Carolina that meets the state's 25/50/25 liability and UM requirements before registration. Compare quotes from multiple South Carolina drivers' insurers, update your garaging address, and confirm your new policy carries the required liability and uninsured motorist limits. A grace period on your out-of-state policy does not substitute for SC-compliant coverage at the time of registration.
Compare & get covered fast
Find and compare auto insurance in minutes, and get your free credit score.
Choose when you pay
Select payment dates that line up with your payday.
Manage everything in one place
Track your policy, manage payments, and request a payment extension right from your dashboard.